17 Sep 2026
SOURCE: CPF Board
CPF savings form an important foundation of our retirement plans. With risk-free interest rates and lifelong, guaranteed payouts through CPF LIFE, CPF can offer greater financial security in our golden years.
So when 56-year-old Pankaj Lunia started retirement planning, he asked a simple question: how much did he want to receive from CPF LIFE each month in retirement?
“I wasn’t really looking at Basic Retirement Sum (BRS), Full Retirement Sum (FRS), Enhanced Retirement Sum (ERS),” he says. “I just wanted to know, what is the maximum I can save with CPF?”
That number turned out to be the ERS, which for Pankaj, translated into about $3,440 a month in CPF LIFE payouts. From there, he explored ways to build his CPF savings towards the ERS and his desired retirement payouts.
Why Pankaj is aiming for the ERS
"I know I am not keen to actively manage large amounts of cash. If it sits in a bank account, I might spend it or let inflation eat away at its value. Funnelling my funds into CPF is my way of creating financial self-discipline."
Choosing reliability
When Pankaj began thinking seriously about retirement in his 40s, he knew what was important to him: long-term stability. Growing up, he had watched his father experience financial highs and lows.
And as someone who had spent decades working with government agencies across the world, he had learned that the best policies are the ones that make a difference to as many people as possible and stand the test of time.
So Pankaj started digging deeper. He spoke to financial advisers, compared retirement systems across different countries and looked closely at how CPF was designed.
He also spoke to people who had been disciplined about saving with CPF and were receiving payouts that comfortably covered their living expenses.
Seeing how CPF worked for them, alongside what he had learned through his own research, gave Pankaj the confidence to commit.
Pairing spreadsheets with CPF planning tools, making CPF transfers and cash top-ups
“Through steady CPF payouts, I felt like having that guaranteed baseline locked in gives me the security to navigate life's unexpected turns.”
With his family’s future in mind, Pankaj took a more structured approach to understanding what his retirement would cost.
This meant building a year-by-year spreadsheet to track his family's estimated expenses, such as daily living costs, healthcare and his children’s university fees, while using the Retirement Payout Planner alongside it.
By setting a target monthly retirement income, he could work backwards to see how much he needed to save and how much his CPF LIFE payouts could cover.
He factored in his own lifestyle too, which included overseas holidays with family and trekking trips in nearby countries.
Then came an opportunity to make some progress. During the COVID-19 period, with reduced spending on his usual lifestyle activities, Pankaj found that he was able to save more than usual.
He used that chance to pay off part of his housing loan and began making cash top-ups to grow his Special Account (SA), which gave him the added benefit of tax relief.
A few years later, when Pankaj turned 55, an increase in top-up limit to the ERS allowed him to transfer even more of his Ordinary Account (OA) savings to his RA, helping him work towards his retirement income goal sooner.
Pairing spreadsheets with CPF planning tools, making CPF transfers and cash top-ups
“I was mentally prepared from a liquidity perspective that the money I’m putting into CPF is not coming back to me so soon. And that is why I was also maintaining that minimum cash pool that I needed in case of emergencies.”
Pankaj sets aside about 12 months’ worth of expenses as an emergency fund. It turned out to be useful when a few unexpected things came his way — from rising costs, to his son getting into university, and getting laid off twice.
“When daily expenses started rising, that was a bit of a surprise, because at first I thought I was doing quite well from a savings perspective,” says Pankaj.
“And when my son got into his dream university, it was a happy surprise, but it also meant my education budget would need to be adjusted.”
Thankfully, with his emergency fund in place, Pankaj was able to tide through these unexpected events.
He also pivoted to starting his own business as a sales consultant. While this meant taking a closer look at his finances and recalibrating his plans in the short term, he remains on track for his longer-term retirement goals.
“The good thing is CPF still continues to earn interest and I can still top up to the prevailing ERS. I realise I’m also checking RPP and my spreadsheet more often, to compare numbers and see if I’m there or not there,” says Pankaj.
"I'd encourage peers to view CPF as a built-in discipline mechanism that protects your future self. In my view, if you figure out what your basic monthly lifestyle costs are and secure that baseline with CPF LIFE, it gives you the confidence to decide how to handle the rest."
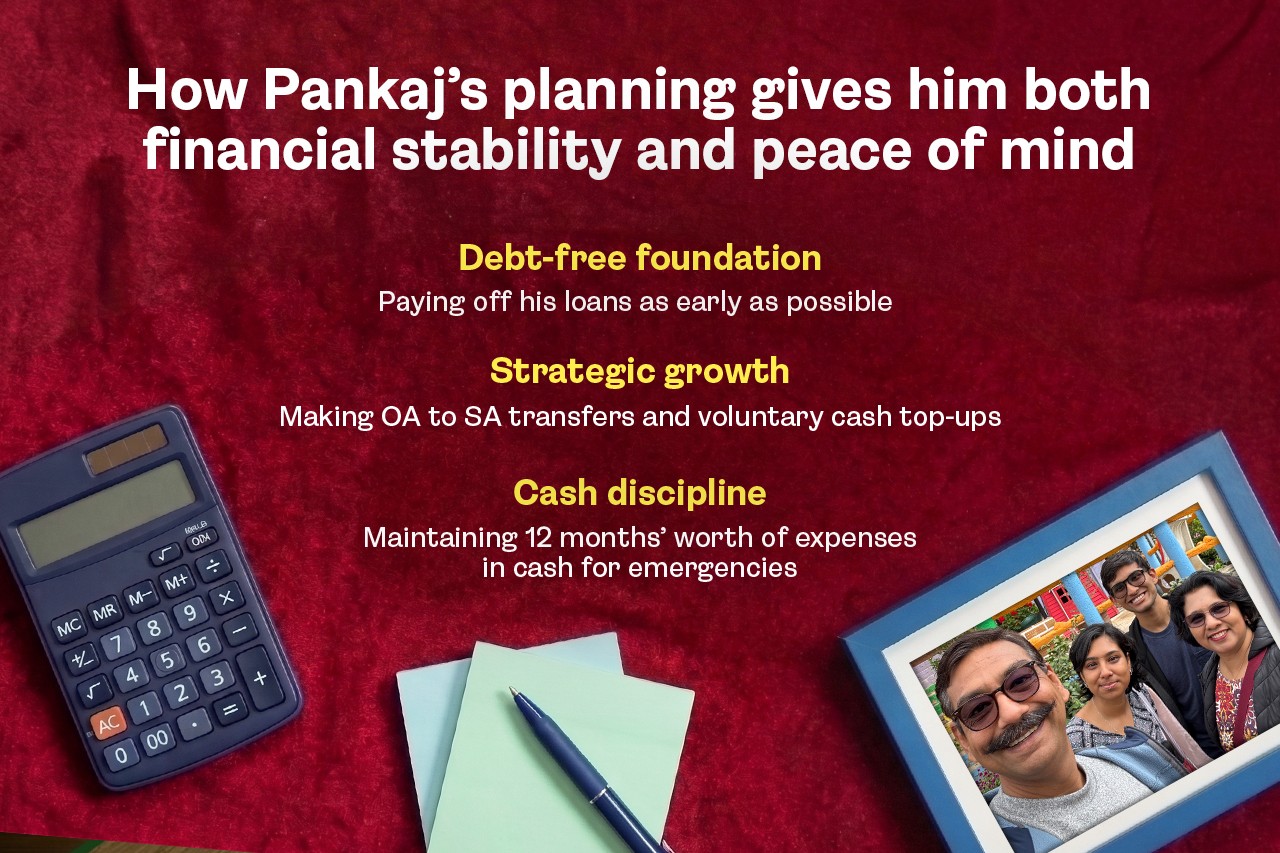
Planning for his next milestone with confidence
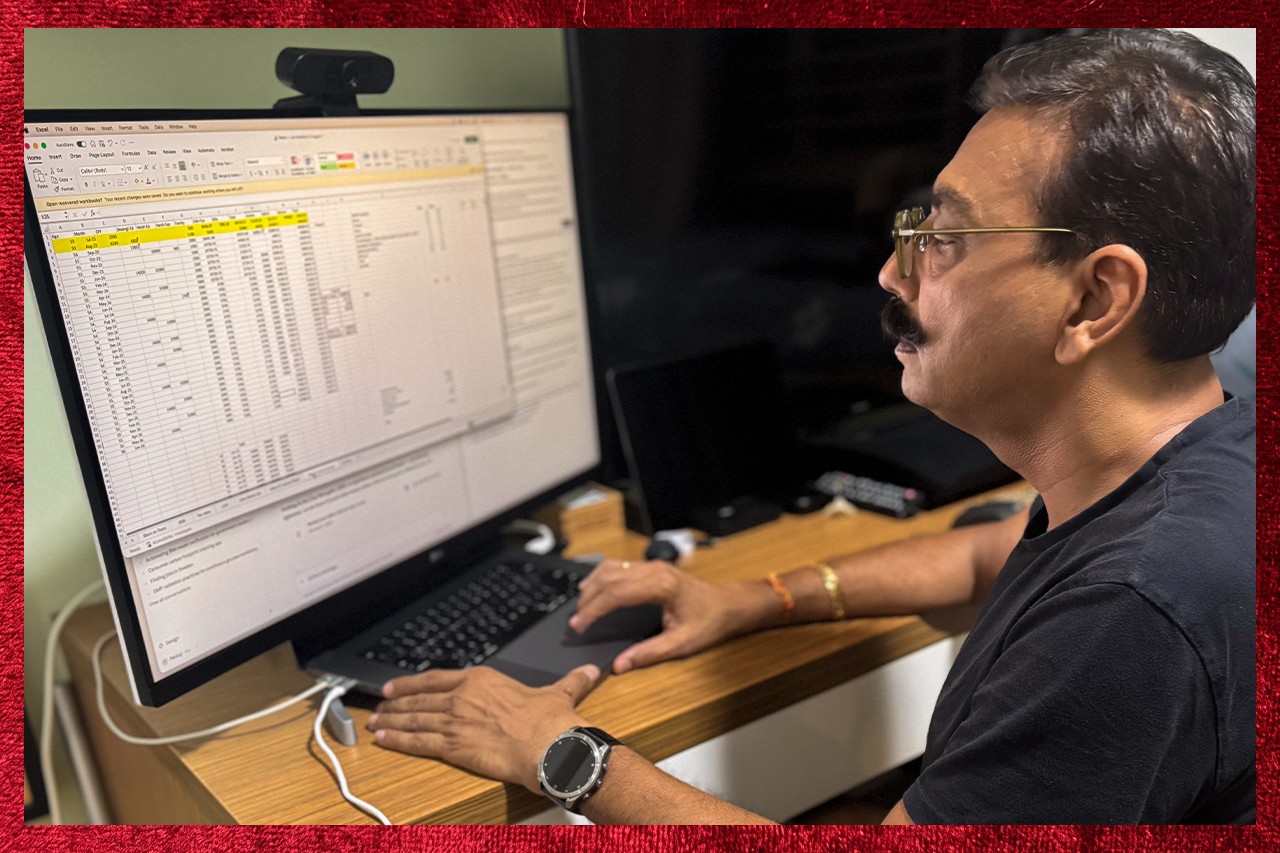
Pankaj believes in setting clear, long-term financial goals. He sees proactive planning as a way to take control of his and his family’s future, sharing that having a roadmap gives him peace of mind as he approaches retirement.
"The RPP helped me define my main retirement goal. I check it annually to monitor my growth and interest. It gives me a clear sense of progress and helps me decide if I should make further top-ups to attain ERS."
Mapping out a retirement that feels right for you
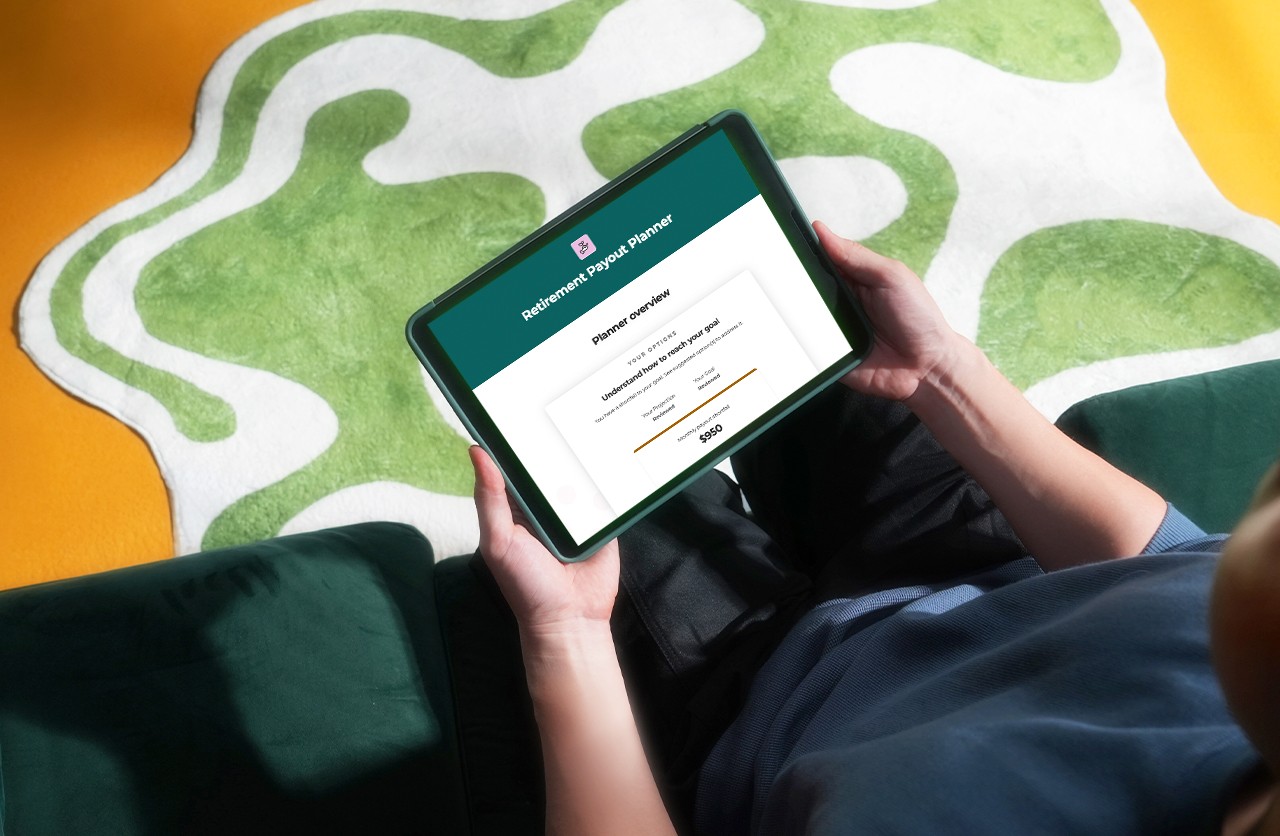
As everyone's retirement journey is unique, there is no single "correct" way to retire. The right strategy is the one that matches your personal risk appetite, financial commitments, and lifestyle aspirations.
Take the first step toward defining your retirement goals today.
Use the goal-setting function on the Retirement Payout Planner to map out your estimated retirement lifestyle costs, explore different retirement sum scenarios, and receive personalised recommendations tailored to your milestones.
Information in this article is accurate as at the date of publication.