17 Sep 2026
SOURCE: CPF Board
You’ve done the research, started building a diversified investment portfolio, and are actively managing your finances to achieve your goals. Naturally, retirement planning and CPF are part of that long-term plan.
CPF is designed to provide a stable financial foundation for your retirement years, and it’s worth taking a closer look at how CPF works to help you be retirement ready. Here are three common questions that even financially savvy Singaporeans have, and what you should know.
Question 1: "Is focusing on returns the best way to think about retirement planning?"
When planning for retirement, it is natural to compare returns across different options. After all, higher returns can make a meaningful difference over time, and many people invest with the aim of growing their wealth for the future.
But framing it as a “returns question” only tells one part of the story.
Beyond how much you accumulate, it also matters how reliable your income is when you stop working, and how well your plans hold up when markets move unpredictably, and over time too – especially when the length of retirement could be longer than anticipated.
This is where CPF plays a distinct role alongside your investments. While market investments are typically used to pursue growth, CPF is designed to support essential needs in retirement: home ownership, healthcare financing, and retirement income.
Through guaranteed interest rates that are not affected by short-term market movements, your CPF accounts help you grow your retirement savings in a way that is more predictable.
As retirement approaches, CPF LIFE, a national longevity insurance annuity scheme, builds on this foundation by providing lifelong payouts. These monthly payouts continue regardless of market conditions after retirement or how long you live, helping to address uncertainties that are difficult to manage through investments alone.
Seen this way, CPF is not intended to replace investing or limit your choices. Instead, it complements your investment strategy by providing a dependable income base, allowing the rest of your portfolio to be structured according to your goals, preferences and risk appetite. This gives you a strong foundation to focus on enjoying a long, fulfilling retirement with confidence.
Question 2: "Is it worth making cash top-ups to CPF when I can chase higher returns in the market?"
When you are trying to balance multiple financial goals, deciding what to do with spare cash is rarely straightforward.
For some, making a cash top-up to your Special Account can feel like a trade-off against investing that cash in the market. It is easy to think that the same money could be working much harder for you if it were invested in the market instead of growing in your CPF.
Rather than viewing cash top-ups and market investments as competing choices, it can be more helpful to consider the different roles they play in a retirement plan.
Market investments are typically used to seek growth and build wealth over time, but they also come with uncertainty. Returns can vary widely, and outcomes depend on market conditions, timing, and risk tolerance.
Cash top-ups serve a different purpose, as they go towards building a more predictable source of retirement income through CPF’s stable and risk-free interest rates.
The question is not whether cash top-ups are “worth it”, but whether your retirement plan strikes the right balance between growth and stability.
If you have enough savings for emergencies, such as 3-6 months of expenses, and essential retirement needs, you may feel more comfortable taking on investment risk elsewhere.
If not, cash top-ups can help you build that retirement foundation and offer added peace of mind. If you can afford it, you can also do both: top up your CPF and invest at least 10% of your take-home pay in the markets.
Question 3: "Can retirement wait if I'm stretching my mortgage to free up cash?"
When you are managing competing goals like servicing your mortgage, maintaining liquidity, and investing, extending your loan tenure seems like a highly practical move.
A longer tenure reduces monthly repayments and frees up cash flow, offering more financial flexibility.
What is less obvious is how this decision can interact with your CPF savings over time, especially as you approach your mid 50s. Here are two longer-term considerations that are easy to overlook when extending your loan tenure
1. How effectively will you be using the freed-up cash?
Stretching your mortgage gives you additional monthly cash flow, which in theory can be invested for potentially higher returns elsewhere. In practice, this works best when it’s backed by a clear investment plan, since outcomes still depend on market conditions.
Without a clear plan, the extra cash may be gradually absorbed into daily expenses or lifestyle spending. And even with one, investment returns are never guaranteed. Either way, a longer mortgage means more accrued interest, so it’s worth thinking about whether the potential returns justify the trade-off.
2. What does this mean for my retirement income later on?
If you are servicing your mortgage with your Ordinary Account (OA) savings, and your home loan extends beyond age 55, the OA savings set aside for those future housing payments won’t be transferred to your Retirement Account (RA). Over time, this may reduce the amount of CPF LIFE payouts you receive.
It’s also worth noting that the CPF contributions allocated to your OA decrease after age 55. So while new OA contributions can still go towards your home loan, there will be less in your OA to fund your housing payments. This means that as you age, you may find yourself increasingly relying on cash for your mortgage.
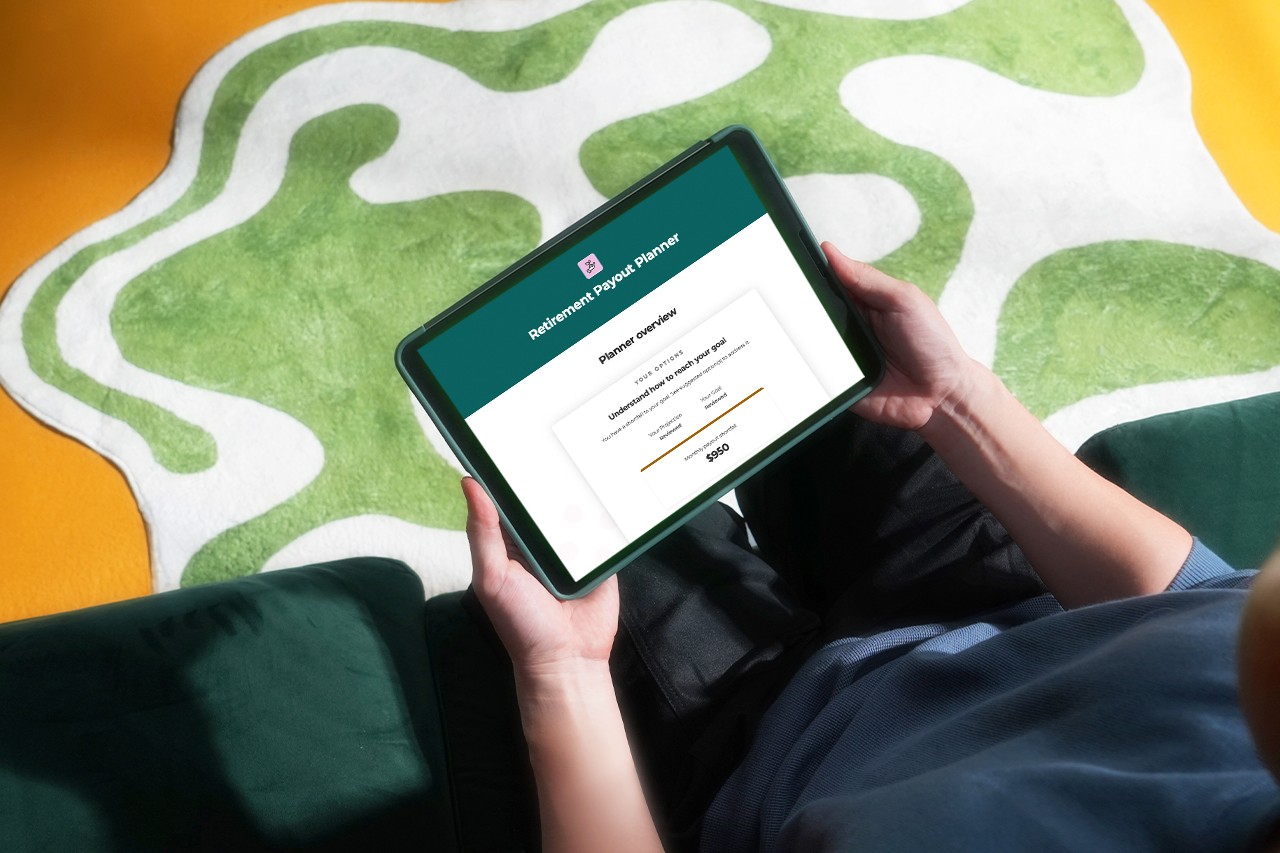
Now that you have worked through the common questions, here’s how you can get a clearer picture of where you stand.
The enhanced Retirement Payout Planner lets you plan flexibly – it projects your future payouts based on your current CPF balances and inputs such as your salary.
Information in this article is accurate as at the date of publication.