13 Nov 2026
SOURCE: CPF Board
Have you thought about how your healthcare needs might change over time?
In Singapore, the gap between life expectancy and health-adjusted life expectancy was about 11 years in 2023. This means that while we are living longer, some of those additional years may be spent in poorer health.
That is why it’s useful to think ahead about your healthcare needs. Whether it is your health insurance coverage or healthcare expenses, what works for you today may not always be what you need in the future.
While there may not be a one-size-fits-all approach, having the right tools and resources can help you better understand your options and make informed decisions along the way.
1) Health Insurance Planner (HIP)
The cost of health insurance can change quite a bit over the years. While a plan may be affordable to you now, it is worth looking at how its premiums could change over time, especially as you get older.
Looking ahead can give you a better idea of what you may be paying in the future, and whether you may need to adjust your coverage along the way.
This is where the Health Insurance Planner (HIP) can come in handy. It lets you compare health insurance plans and assess the long-term affordability of your preferred coverage.
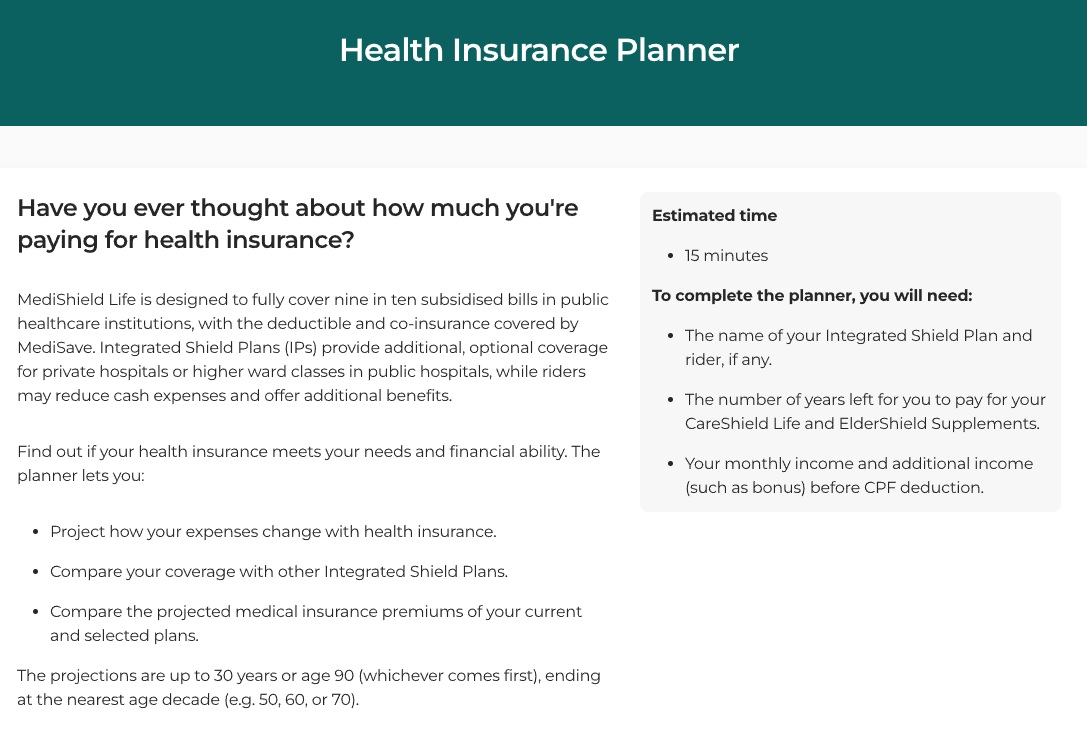
With the HIP, you can:
Make long-term, personalised projections of your MediSave savings and health insurance premiums. This gives you a better idea of how your MediSave savings and premiums may change over time.
Compare key benefits, features, and premiums across Integrated Shield Plans (IPs) for your preferred ward type. You can see how the plans differ in terms of coverage and premiums, based on the ward type you are considering.
Project long-term premiums for your selected IP and rider (including the new IP riders). This helps you see how your premiums and out-of-pocket costs may change over the next 30 years, or up to age 90, whichever is earlier.
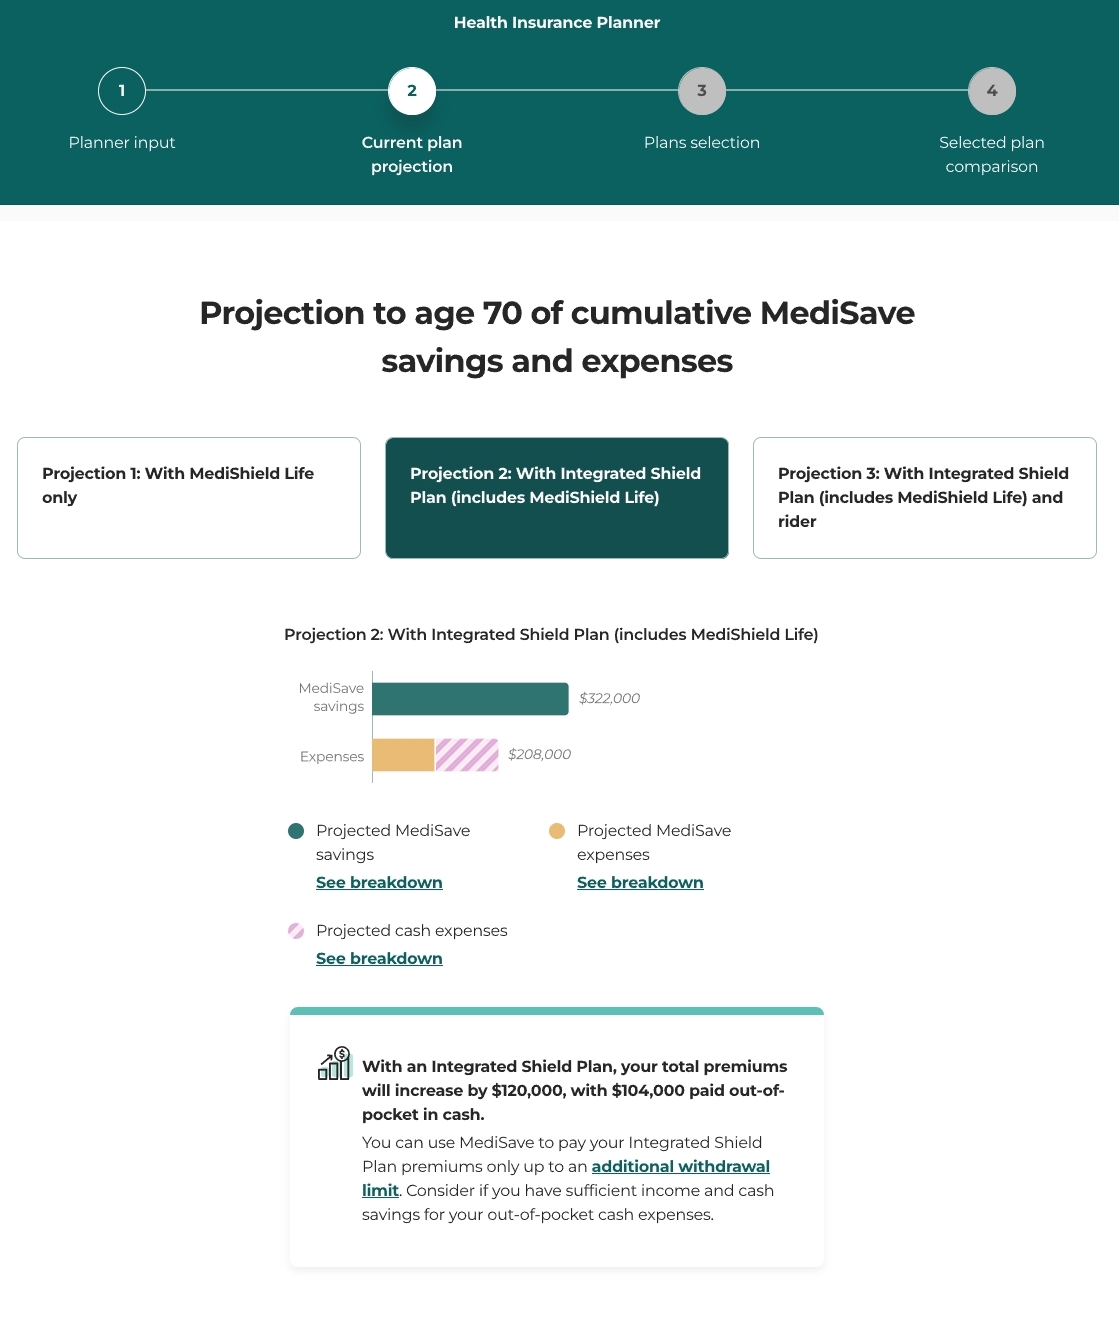
Example of projected MediSave savings and healthcare expenses shown in the HIP
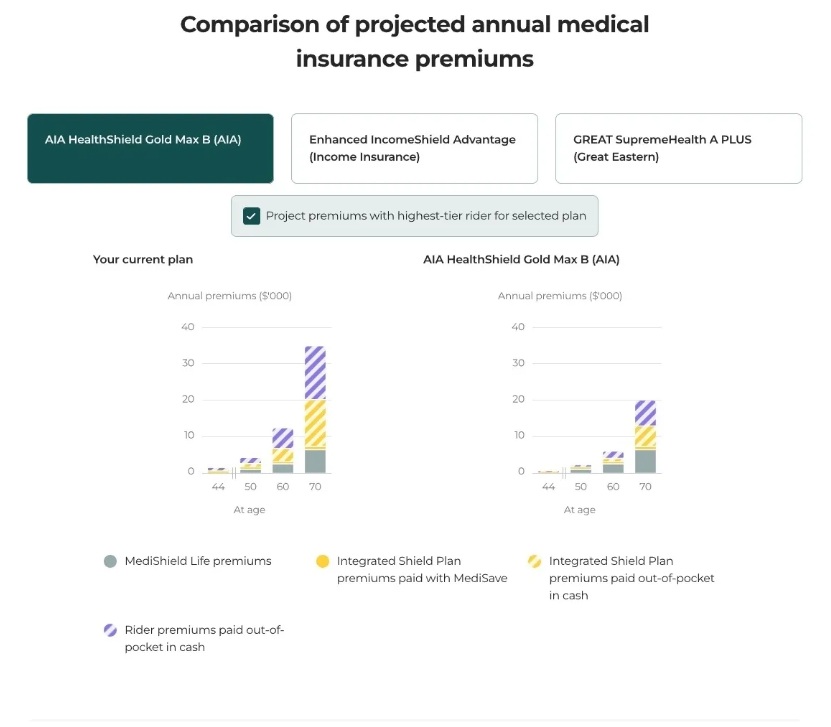
Example of projected annual health insurance premiums shown in the HIP
Note: The figures shown are for illustration purposes only. Your projections will depend on the information provided in the HIP.
Once you have completed the HIP, you can download your personalised report and refer to it without having to fill in the planner again. This can also help inform your discussion with your insurance agent if you are considering changes to your coverage.
2) MediSave/MediShield Life claims calculator
Healthcare bills can be hard to plan for, especially when you may not know how much can be covered under MediSave and MediShield Life.
The MediSave and MediShield Life claims calculator gives you an estimate of how much you may be able to claim from MediShield Life and withdraw from MediSave for eligible treatments.
How does MediSave work?
As you work and contribute to your CPF, part of your contributions is set aside in your MediSave Account.
Your MediSave savings can be used for eligible healthcare expenses such as hospitalisation, day surgery and certain outpatient treatments. They can also be used to pay for approved medical insurance premiums.
Staying protected from large hospital bills with MediShield Life
MediShield Life, on the other hand, helps with large hospital bills and selected costly outpatient treatments. Singapore Citizens and Permanent Residents (PRs) are covered for life, regardless of age or health condition.
So, how much MediSave can you use, and how much can you claim under MediShield Life?
Based on details such as your treatment, medical institution and hospitalisation, the MediSave/MediShield Life claims calculator gives you an estimate of how much you may be able to claim from MediShield Life and/or withdraw from MediSave.
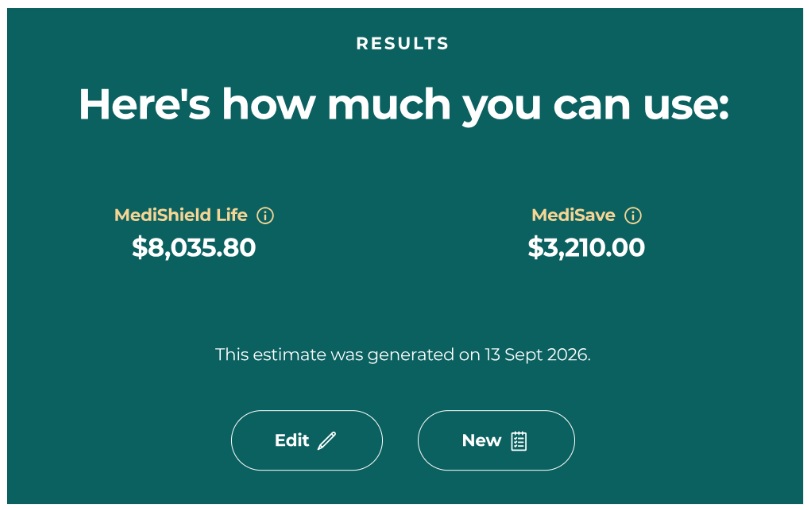
Example of the estimated MediShield Life claim and MediSave withdrawal amounts shown by the calculator
Do note that the amounts shown by the calculator are estimates and may differ from the actual MediSave amount you can use or MediShield Life amount you can claim.
3) Consider joining CareShield Life if you are not already enrolled
Long-term care may not be something you need now, but your care needs can change over time. CareShield Life provides monthly cash payouts for life if you are severely disabled and need personal and prolonged medical care.
Depending on when you were born, you may already be covered under CareShield Life:
Born in 1980 or later: You are automatically covered from age 30.
Born in 1979 or earlier: If you are not already enrolled, you can choose to join CareShield Life if you do not have any pre-existing disability.
To receive monthly payouts, you will need to be assessed by a Ministry of Health-accredited assessor who will confirm that you are unable to perform three or more of the six Activities of Daily Living (6 ADLs) listed below.
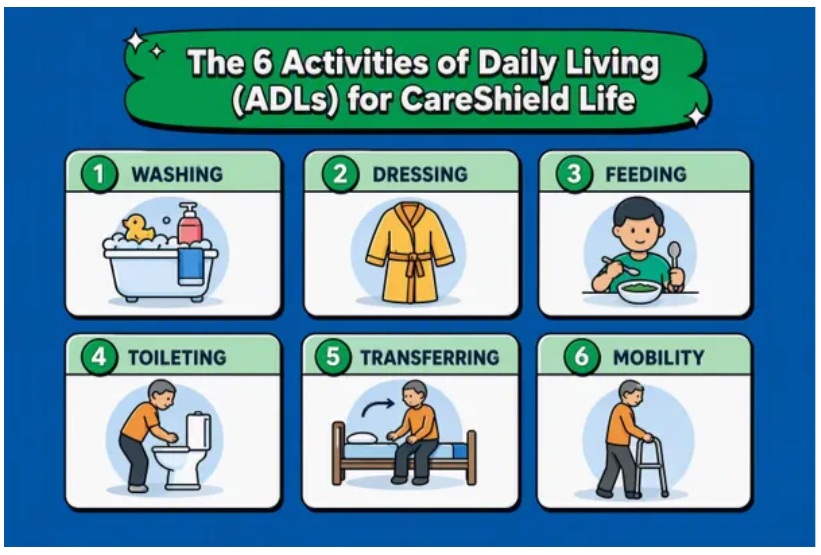
Image created with AI assistance
If you are currently covered under the ElderShield, you may want to consider switching to CareShield Life.
Long-term care needs can continue for many years, which is where the duration of the payouts can make a difference. CareShield Life offers higher monthly payouts that continue for as long as you remain severely disabled. In contrast, ElderShield payouts are limited to five or six years, depending on your plan.
Do note that joining CareShield Life will require additional premiums, which can be fully paid using MediSave.
Useful CPF calculators and resources for your healthcare planning
You do not need to review every part of your healthcare planning at once. A good place to start is with what is most relevant to you now.
Start with one area, such as checking your health insurance coverage or getting an estimate of your healthcare costs. You can always come back to the other areas later!
The information provided in this article is accurate as of the date of publication.


